The Hidden Formula That Decides Whose Flooded House Gets Fixed First
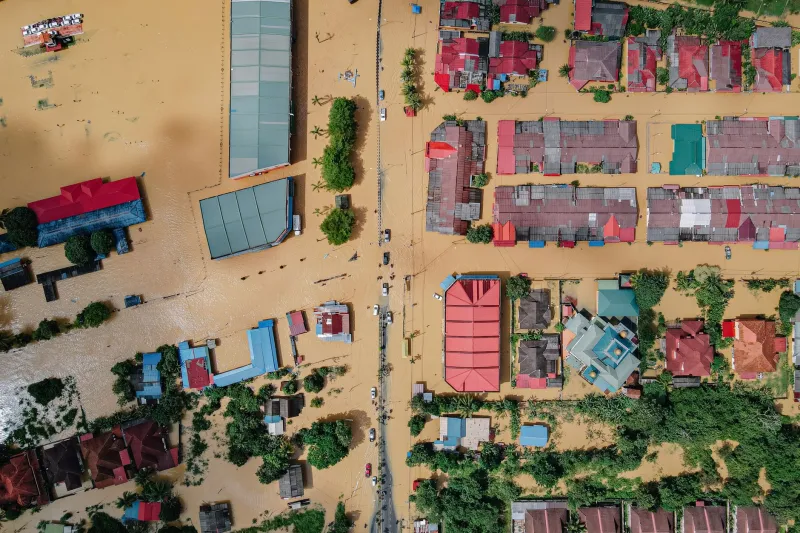
Two houses on the same block. Same storm. Same knee-deep water. Same ruined drywall and dead refrigerator. One family gets a federal check in a few weeks. The other spends months in appeals, resubmitting photos and forms, watching the timeline stretch into the next season.
That gap is not a glitch. It is the system working the way it was built.
When a major storm hits, the United States does not simply hand out disaster aid like a raffle. It scores the disaster, scores the damage, scores the insurance situation, and scores the local government’s ability to pay its share. Some of that math happens before a single resident fills out an application. Some of it happens after. Almost none of it is visible from your front porch.
Two houses, one storm, two different checks
Start with the declaration itself. A governor asks Washington for help. Federal officials look at damage assessments, local capacity, and formulas that weigh the scale of the wreckage against the state’s population and tax base. That determines whether a disaster gets a federal declaration at all — and which programs switch on.
Then comes the split that confuses everyone. One bucket helps individuals and households. Another reimburses local governments and nonprofits for debris removal, repairs, and emergency work. A third tries to fund long-term mitigation so the next storm does less damage. Each bucket has its own rules, its own paperwork, and its own version of a credit report.
For a homeowner, the first hidden score is often insurance. Federal disaster aid is not designed to make you whole before your insurer does. It is designed to fill gaps — and only certain gaps. If you have flood insurance, the federal process waits for that claim to play out. If your insurer denies you, that denial letter becomes a strange kind of ticket: frustrating, but sometimes necessary to prove there is a gap left to fill.
That is why the neighbor with the clear flood policy and the tidy claim file can move faster than the neighbor whose policy was thin, late, or disputed. Same damage. Different paper trail.
The scoreboard is a spreadsheet, not a credit bureau
There is no literal FEMA credit score for a household. But there are proxies that function like one: documentation, insurance status, income, pre-disaster housing condition, and how quickly local officials verify the damage.
After a disaster, teams fan out to assess homes. They note what is damaged, how badly, and whether it was already falling apart before the storm. A roof that was patched with tarps for three years tells a different story than a roof that was replaced last spring. The system is not trying to be cruel. It is trying to avoid paying for deferred maintenance with disaster dollars. But the result can feel arbitrary when your kitchen is in a pile and someone is asking whether the cabinets were already outdated.
Then there is the duplication-of-benefits rule. You cannot get paid twice for the same loss. Sounds simple. In practice, it means disaster aid can stall while insurance, loans, and charitable help sort themselves out. The Small Business Administration may offer a disaster loan. A church may hand out gift cards. A cousin may start a GoFundMe. None of those are the same as a federal grant, but they all enter the paperwork blender.
The family that understands this early — and keeps every receipt, photo, denial letter, and contractor estimate in one folder — is not gaming the system. It is speaking the system’s language.
Insurance is the first referee — and it rarely calls it clean
Most people think of insurance as the safety net and government as the backup. In disaster recovery, it often works the other way around: the federal process is constantly asking what insurance will or will not do.
That creates a cruel timing problem. Insurers can take weeks or months. Adjusters are overloaded. Denials get appealed. Meanwhile, the federal application window keeps moving. Residents who wait for a final insurance answer can miss deadlines. Residents who apply too early can get lowballed because their file is incomplete.
The practical advice from people who work these cases is boring and essential: apply, document, and update. Do not assume one phone call fixes anything. Do not assume the first estimate is the last word. Ask what specific document is missing. Ask whether the file is waiting on insurance, verification, or an appeal. Ask for the application number and write it down.
The matching-funds trap nobody puts on a yard sign
Here is the part that separates a fast recovery from a slow one at the community level: local matching funds.
Federal disaster programs often require state and local governments to pay a share of the cost. The federal government might cover most of a project, but the town still has to come up with the rest. A wealthy suburb with a strong tax base and a grant writer on staff can move. A small town with a shrinking budget and one overworked clerk cannot always do the same, even when the damage is worse.
That is the invisible credit score of a place. It is not your personal credit. It is your ZIP code’s ledger — tax base, staffing, prior grant experience, and whether local leaders can front money while waiting for reimbursement. Two towns can have identical blown-down trees and flooded basements, and one gets the project funded first because it can afford to say yes.
What actually moves your file
There is no magic sentence that speeds up disaster aid. But there are patterns.
People who get help faster tend to have photos before and after, receipts for major purchases, insurance documents, contractor estimates, and a clear list of what was damaged. They call local emergency management, not just a federal hotline. They ask their county or city whether the community is pursuing public assistance or mitigation money. They keep a paper trail and they follow up with dates and names.
They also understand that disaster aid is not a single check from a single agency. It is a stack of programs with different doors. Some open for renters. Some open for homeowners. Some open for businesses. Some open only for local governments. Knowing which door you are supposed to knock on is half the battle.
The ledger behind your ZIP code
The uncomfortable truth is that disaster recovery in America is not just about need. It is about scoring, sequencing, and capacity. That is not a conspiracy. It is how a sprawling federal system tries to ration limited money across enormous damage. But it does mean that two neighbors with similar wreckage can end up with very different outcomes — and the difference is often decided by paperwork, insurance, and local fiscal health before anyone ever looks at the hole in your roof.
So when the next storm comes, do not just ask whether help is coming. Ask how your file is being scored, who is holding the paperwork, and whether your town can afford its share. The answer explains a lot more than the weather report.